

Sumio: Net Worth Tracker
by Fiduciary
3.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.8
- Price
- Free
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
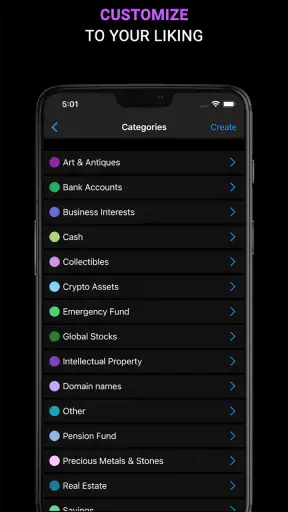
 Analysis by Getfullapps
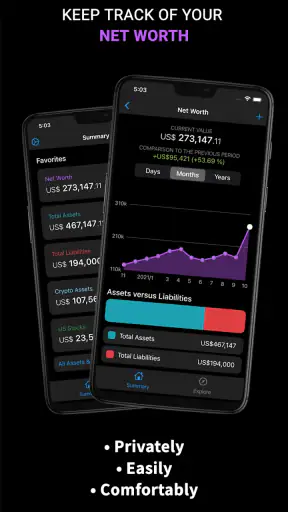
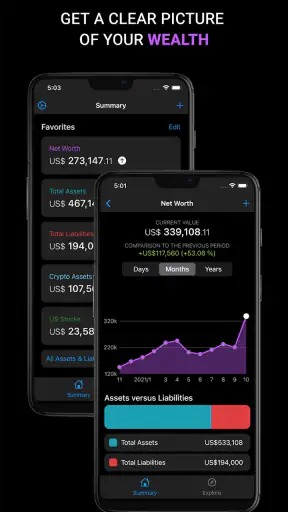
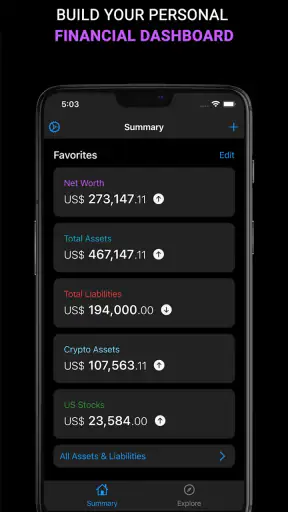
I like finance apps that help me see the whole picture without pretending to replace a bank, broker, or spreadsheet. Sumio: Net Worth Tracker takes that narrower, more useful approach. It is a free finance app from Fiduciary for recording and following net worth, investments, stocks, funds, and other assets. After spending time with it, I found the main appeal is not flashy market analysis; it is the simple habit of bringing scattered financial information into one personal snapshot.
That distinction matters. If you want a live trading terminal, automatic banking connections, or detailed tax software, this is probably not the right destination. If you want a calm way to check whether your overall financial position is moving in the direction you expect, Sumio is much easier to understand. Its best use is as a repeatable personal dashboard, not as a complete financial command center.
Building a dependable financial baseline
The first useful step is to treat the app as a baseline rather than a place to chase daily market noise. I would begin by entering the accounts and assets that matter most to my overall position: cash, investments, funds, property or other valuable holdings, followed by debts if I want the net figure to reflect them. The quality of the result depends less on entering everything immediately and more on using the same categories consistently.
For example, adding an investment account under one name and then later recreating the same holding under another can make the total harder to trust. I found it more practical to decide on a small naming system before filling the app. A name such as “long-term fund” is more useful than a vague label, especially when I return later and need to know whether I am editing a holding, an account, or a general asset.
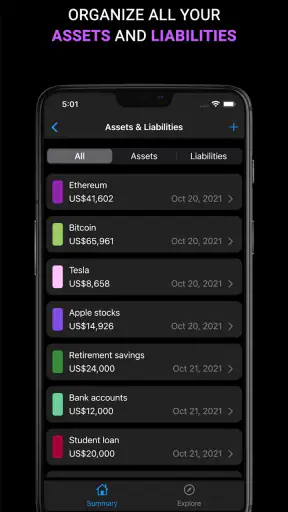
Sumio is particularly suitable for people whose finances are spread across several places. A savings account, a workplace investment plan, a few individual stocks, and a vehicle can feel unrelated when viewed separately. In a net-worth tracker, they become parts of one broader position. That change in perspective is the reason I would recommend it to someone who keeps checking balances but still cannot answer a basic question: “Am I actually becoming financially stronger?”
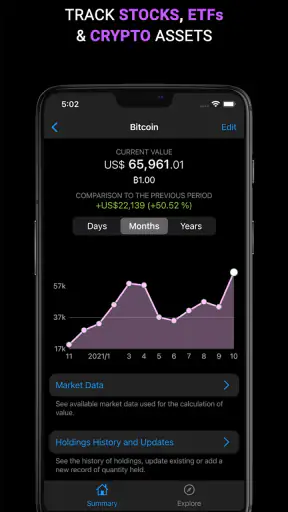
The app’s store summary covers net worth, investment portfolios, stocks, funds, and assets, and that range gives it more flexibility than a simple expense log. It is not focused on recording every coffee or household purchase. Instead, it helps with the higher-level balance sheet. I would use a budgeting app alongside it if monthly spending control were my main concern.
A realistic monthly routine
Imagine checking finances on the first weekend of each month. I would open Sumio, update cash balances, adjust investments or funds to their current values, and review any major asset or debt changes. The point is not perfect minute-by-minute accuracy. The point is to make the same check often enough that an unexpected change becomes visible instead of remaining hidden across several separate services.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This routine also reduces a common mistake: reacting to one account in isolation. A market drop can look alarming when I only view an investment screen, while the total picture may be less dramatic because cash or another asset has remained stable. Conversely, a rising portfolio can create false confidence if debt has grown at the same time. Looking at the combined figure encourages better questions.
I would keep a short note outside the app about what was updated and when, particularly during the first few reviews. That is not a special Sumio feature; it is a practical habit that makes manual tracking easier to audit. If the total suddenly looks wrong, I can retrace the changes rather than guessing which entry was edited.
What the interface is good at, and what it is not
The strength of this kind of app is clarity. A focused net-worth view can be less distracting than a bank application filled with transactions, offers, and account-specific messages. Sumio gives the user a place to think in terms of ownership and obligations rather than individual payment events.
The trade-off is manual responsibility. A tracker is only as current as the information entered into it. Anyone expecting automatic synchronization with every financial provider should examine the workflow carefully before making it their only source of truth. For me, that limitation is acceptable when the goal is a deliberate monthly or weekly review, but it would be frustrating for someone who wants every balance refreshed without effort.
The current release is version 1.9.18, and it runs on Android starting with version 7.0. It is rated for Everyone, so the basic audience is broad, although financial decisions themselves still require adult judgement. The app has passed ten thousand installs and holds a 3.8 average from seventy-eight ratings. I read that as a modest sign of interest rather than proof that it will suit every financial setup.
Settings, shortcuts, and repeatable habits
Before entering a large amount of information, I would spend a few minutes checking the available settings and display preferences. In a tracker like this, small choices about presentation can affect whether I keep using it. If the app lets me choose how values are shown, I would select the currency and formatting that match my everyday accounts. If it offers a way to control how categories or assets are displayed, I would keep the structure simple enough to understand at a glance.
I would also check whether the app’s update behavior matches my routine. Some people want to record a value whenever they make a transaction; others prefer a scheduled review. Sumio works best when the method is intentional. A tracker filled with irregular guesses can be less useful than one updated less often but with consistent rules.
One setting-related trade-off deserves attention: detail versus speed. Recording every individual security may make a portfolio more informative, but it also creates more maintenance. Recording only broad holdings is quicker, yet it can hide how one part of the portfolio affects the total. I would use detailed entries for investments I actively monitor and broader categories for assets whose exact daily value is not important to my decisions.
That approach is especially useful for households. One person may care about individual stocks, while another only needs to know the combined value of long-term savings. A shared naming convention can prevent the dashboard from becoming a personal filing system that only one user understands. Sumio does not need to become a perfect accounting ledger to be useful; it needs to remain readable when I return after a busy week.
Faster patterns for regular reviews
The fastest workflow I found is to update in order of impact. I would start with the largest balances, then review smaller assets and liabilities. If time is limited, this gives a more meaningful estimate than spending several minutes correcting a minor item while leaving a major investment value unchanged.
Another useful pattern is separating “review” from “research.” When I open the app for a net-worth check, I would update known values and leave investment analysis for another moment. Mixing the two activities makes it easy to spend time reading market information without actually maintaining the personal record. Sumio is most valuable when it supports a short, repeatable check rather than becoming another source of financial distraction.
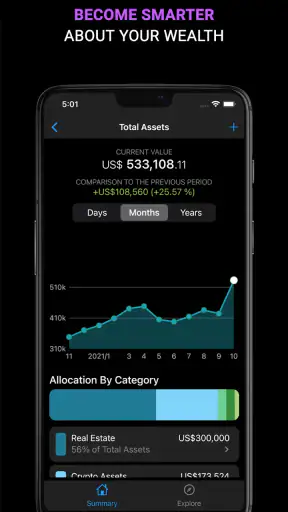
I also prefer comparing periods rather than judging a single number. A total by itself has little meaning. A sequence of carefully maintained snapshots can show whether progress is steady, seasonal, or being driven by one unusually strong or weak asset. Even without sophisticated forecasting, this helps me distinguish a temporary fluctuation from a change in my financial habits.
For people with irregular income, the app can serve as a quarterly checkpoint instead of a monthly one. Freelancers, contractors, or anyone with variable earnings may find that a broader review fits reality better than forcing a rigid schedule. The important part is to record the same types of information each time, so the comparison remains fair.
Where it compares well with familiar alternatives
Compared with a spreadsheet, Sumio is more approachable for someone who wants a dedicated place to view assets and investments without designing formulas and layouts first. A spreadsheet wins when I need custom calculations, detailed historical records, or unusual categories. It also makes backups and exports part of my own process rather than relying on the behavior of an app. For a user who enjoys building a personal financial model, a spreadsheet may remain the better tool.
Compared with a budgeting app, Sumio answers a different question. Budgeting tools usually focus on income, bills, spending categories, and cash flow. Sumio is more concerned with what I own and owe overall. Someone trying to stop overspending should begin with a budget. Someone who already manages spending but lacks a consolidated view may get more from a net-worth tracker.
Compared with a brokerage application, it is broader but less specialized. A broker is the correct place to place trades, inspect order details, and manage a specific investment account. Sumio is useful when I want that account considered alongside cash, funds, stocks, and other assets. I would never treat the tracker as a replacement for the official record held by a financial institution.
Compared with an automatic aggregation service, Sumio may feel slower because it depends more on deliberate updates. The benefit is a potentially calmer workflow with less emphasis on constant synchronization. The disadvantage is obvious: forgotten updates can make the picture stale. This is the central choice a new user should make before committing to it.
Advanced limits worth understanding
Experienced users should be careful not to confuse tracking with valuation. An entry in Sumio is a representation of an asset, not independent confirmation of its current worth. Illiquid property, collectibles, private holdings, or vehicles can be especially subjective. I would update those values conservatively and record them using the same method each time rather than changing them whenever I feel optimistic.
Investment performance can also be misleading if deposits and withdrawals are not considered. A higher portfolio value may come from adding money, not from earning a return. Likewise, a lower figure may reflect a withdrawal for a planned purchase. Sumio can help me observe the overall result, but I still need to interpret why it changed. For serious performance measurement, a dedicated investment analysis tool or a carefully designed spreadsheet may be more appropriate.
Privacy is another reason to think about the level of detail. I would avoid treating a personal tracker as a place to store unnecessary account credentials or sensitive notes. Enter only the information needed for the overview, use a sensible device lock, and remember that convenience should not encourage careless handling of financial details.
The free price makes trying the basic workflow easy, but the app also lists in-app purchases ranging from two dollars and ninety-nine cents to twenty-nine dollars and ninety-nine cents per item. I would test the core experience first and only pay for an optional feature if it clearly saves time or improves the review process. That is more sensible than assuming every paid addition is necessary.
There are also users who should skip this app. If you need automatic, continuously refreshed balances, advanced tax reporting, household permissions, or detailed investment returns, a more specialized service will likely fit better. If your finances are extremely simple, a note or spreadsheet may be enough. Sumio makes the most sense in the middle: for someone with several assets who wants structure without building a full financial system.
My verdict after making it a habit
I see Sumio as a practical companion for people who want to maintain a net-worth habit without turning personal finance into a daily project. Its value grows when I use consistent categories, update the biggest items first, and review changes over time instead of reacting to one balance. Those habits matter more than entering an impressive amount of detail.
Fiduciary has positioned this as a focused finance app, and that focus is both its appeal and its boundary. It brings stocks, funds, investments, and wider assets into one view, but it does not remove the need for judgement or regular maintenance. I appreciate that trade-off when I want a deliberate snapshot; I would choose something else when automation or accounting depth is the priority.
At no cost to download, with an Everyone age rating and support for older Android devices from version 7.0 onward, it is accessible enough to try without reorganizing my entire financial life. The modest rating suggests I should approach it with realistic expectations rather than assuming universal polish. Still, for a reader who has balances scattered across accounts and wants a simple routine for seeing the larger picture, Sumio: Net Worth Tracker is worth trying as a personal financial checkpoint.
My final recommendation is to start small: add the assets that shape the majority of your net worth, choose clear names, complete one review, and then decide whether the process feels sustainable. If you find yourself returning regularly and understanding your position more quickly, the app is doing its job. If manual maintenance feels like a burden from the first session, a more automated alternative will probably serve you better.
Pros
- Tracks assets, debts, and net worth in one organized dashboard.
- Supports custom accounts and categories for flexible financial planning.
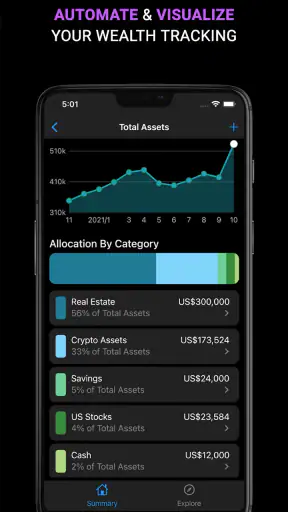
- Clear charts make changes in wealth easier to understand over time.
- Useful reminders can help maintain regular updates and financial habits.
- Privacy-focused design may appeal to users avoiding social finance platforms.
Cons
- Manual data entry can become tedious without automatic bank synchronization.
- Some advanced features may require a paid subscription.
- Values can become inaccurate if accounts and liabilities are not updated.
- Investment tracking may lack the depth of dedicated portfolio apps.
- Users may need time to configure categories and goals to fit their needs.
FAQs for Sumio: Net Worth Tracker
What is Sumio: Net Worth Tracker used for?
Sumio: Net Worth Tracker is a personal finance app designed to help you monitor your net worth in one place. You can record assets such as bank accounts, investments, property, and vehicles, then subtract liabilities like loans or credit card balances. The app presents your financial position through dashboards and charts, making it easier to follow progress over time.
Do I need to connect my bank accounts to use Sumio?
No, connecting a bank account is not necessarily required to use Sumio. You can manually add accounts, assets, debts, and their values if you prefer not to share financial access. Depending on your country and the version of the app, automatic synchronization may be available through supported providers. Always review permissions, supported institutions, and privacy terms before enabling connections.
Is Sumio: Net Worth Tracker free to download?
Sumio can generally be downloaded at no initial cost, but some features may require a subscription or in-app purchase. Premium options can include more detailed tracking, additional account types, advanced charts, or enhanced customization. Before starting a trial, check the current pricing, renewal conditions, and cancellation process shown in the App Store or Google Play listing.
How does Sumio calculate net worth?
The app calculates net worth by adding the current values of your assets and subtracting your outstanding liabilities. The accuracy of the result depends on how complete and up to date your information is. Manually entered balances may need regular updates, while synchronized accounts can reduce maintenance where supported. Investments and property values may also require user verification.
Is Sumio safe for tracking personal financial information?
Sumio handles information that can be highly sensitive, so you should review its privacy policy and security details before entering financial data. Use a strong device passcode, enable biometric protection if available, and download the app only from an official store. If linking accounts, confirm what access is requested and avoid entering unnecessary confidential information.

Sumio: Net Worth Tracker
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@sumio.app, visit https://www.sumio.app, or review their https://www.sumio.app/privacy.










